


Netflix Inc Stock (NFLX) Moved Up by 3.75% on Sep 14: What Investors Need To Know



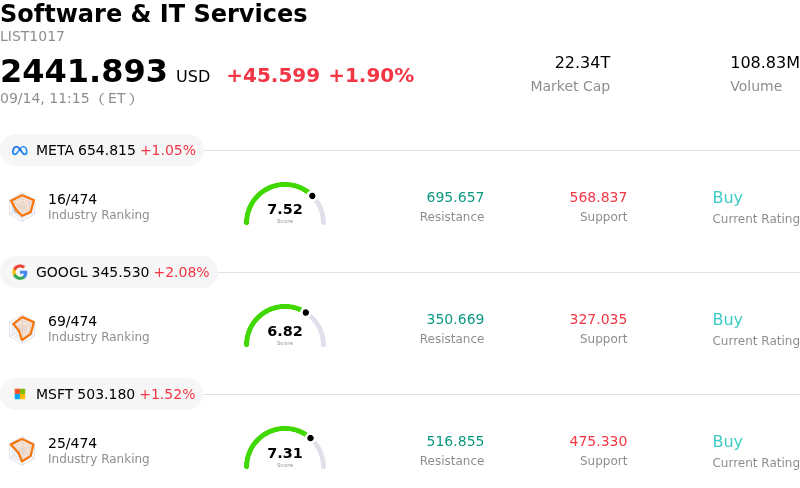
Netflix Inc (NFLX) moved up by 3.75%. The Software & IT Services sector is up by 1.90%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 1.05%; Alphabet Inc Class A (GOOGL) up 2.09%; Microsoft Corp (MSFT) up 1.53%.
What is driving Netflix Inc (NFLX)’s stock price up today?
Shares of Netflix experienced notable upward momentum as positive Wall Street commentary and favorable survey data bolstered investor confidence in the streaming leader’s long-term growth trajectory. A key catalyst for the session was a price target upgrade from Evercore ISI, which reaffirmed an Outperform rating while highlighting accelerating consumer adoption and improving subscriber metrics across key primary markets. Analyst survey results pointed to multi-year high penetration rates in the United States and record engagement levels in major international territories such as Japan, signaling durable competitive advantages.
The positive price movement reflects growing market appreciation for Netflix’s multi-tiered monetization strategy and expanding content mix. Proprietary survey data demonstrated that the standard ad-supported tier continues to perform as an effective retention mechanism, diverting price-sensitive consumers from canceling subscriptions while opening lucrative advertising revenue channels. Furthermore, the company’s strategic push into live events, high-profile sports programming, and short-form video feeds is driving higher platform engagement and customer satisfaction, effectively insulating the platform against broader media cord-cutting trends.
From an institutional research perspective, Netflix’s fundamental narrative remains firmly supported by expanding operating margins and disciplined content spending. As management maintains focus on high-margin ad products, regional pricing optimization, and opportunistic share repurchases backed by strong free cash flow generation, the stock’s compelling valuation relative to its medium-term earnings power continues to attract institutional buyers, fueling intraday strength despite recent sector-wide volatility.
Technical Analysis of Netflix Inc (NFLX)
Technically, Netflix Inc (NFLX) shows a MACD (12,26,9) value of -0.960, indicating a neutral signal. The RSI at 55.843 suggests neutral condition and the Williams %R at 38.506 suggests buy condition. Please monitor closely.
Media Coverage of Netflix Inc (NFLX)
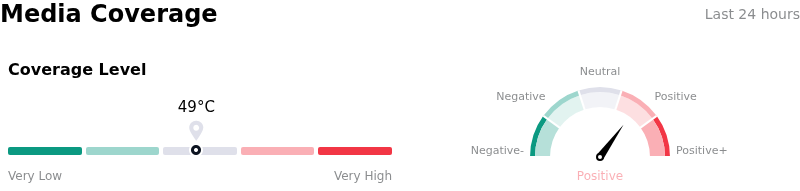
In terms of media coverage, Netflix Inc (NFLX) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Netflix Inc (NFLX)
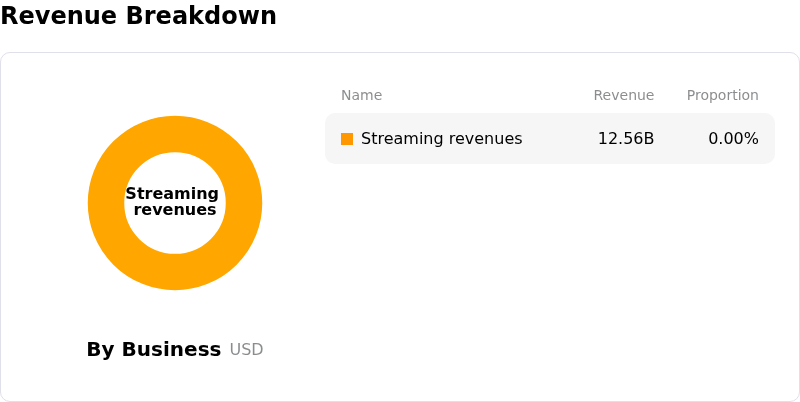
Netflix Inc (NFLX) is in the Software & IT Services industry. Its latest annual revenue is $45.18B, ranking 12 in the industry. The net profit is $10.98B, ranking 10 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $95.32, a high of $135.00, and a low of $70.00.
More details about Netflix Inc (NFLX)
Company Specific Risks:
- Decelerating Revenue Growth and Subscriber Saturation: Projected top-line growth is slowing to low double digits alongside declining watch-time engagement per member, elevating long-term subscriber churn risks and signaling core market saturation.
- Margin Compression from Escalating Live Sports Rights: Ramping annual content spend toward $20 billion—heavily inflated by major multi-year live sports commitments such as NFL rights—is compressing operating margins before advertising monetization fully materializes.
- Valuation Premium and Wall Street Target Reductions: Trading at a forward P/E ratio over double the consumer discretionary industry average leaves the equity vulnerable to sharp intraday sell-offs, exacerbated by institutional price target cuts down to the $75–$85 range.
- Regulatory Probes and International Pricing Pushback: Aggressive subscription price hikes in primary overseas markets face consumer retention risks, while foreign regulatory scrutiny regarding digital streaming pricing structures poses ongoing operational headwinds.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.