


AECOM Stock (ACM) Closed Up by 11.08% on Nov 17: A Full Analysis


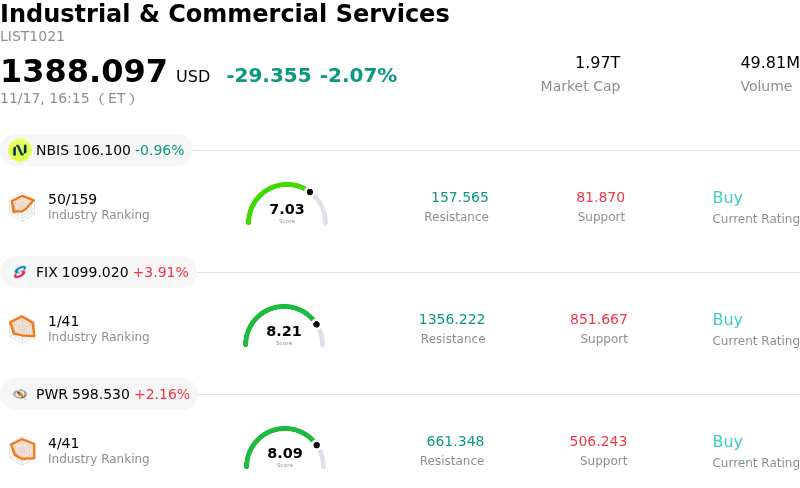
AECOM (ACM) closed up by 11.08%. The Industrial & Commercial Services sector is down by 2.07%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Nebius Group NV (NBIS) down 0.96%; Comfort Systems USA Inc (FIX) up 3.91%; Quanta Services Inc (PWR) up 2.16%.
What is driving AECOM (ACM)’s stock price up today?
AECOM experienced substantial upward momentum following the release of its fourth-quarter and full-year fiscal earnings report, which outperformed Wall Street expectations on key profitability metrics. The infrastructure consulting leader posted adjusted earnings per share that comfortably surpassed consensus estimates, driven by solid execution across core design and international engineering services. The results provided clear relief to investors, demonstrating operational resilience after prior periods were clouded by project-specific charges in the construction management business.
The primary catalyst for institutional buying was the company's remarkable margin performance. AECOM achieved record quarterly levels in adjusted operating and EBITDA margins, highlighting the ongoing strategic pivot toward higher-value professional consulting, advisory, and digital services. Operating profitability in the international segment was particularly robust, benefiting from disciplined cost management and a favorable project mix. In addition, AECOM closed the fiscal year with record project wins and an all-time high total backlog, underpinned by a book-to-burn ratio well above parity. This expanding order book substantially bolsters medium-term revenue visibility and reaffirms the company's strong positioning to capture global infrastructure spend.
Market sentiment was further bolstered by encouraging forward guidance for the upcoming fiscal year. Management initiated full-year adjusted earnings per share and EBITDA targets that matched or exceeded analyst projections, signaling confidence in steady organic net service revenue growth and sustained margin progress toward multi-year operating goals. Investors also welcomed better-than-expected free cash flow generation, which finished ahead of the company's prior outlook. Underscoring its balance sheet health and disciplined capital allocation, the board approved a double-digit percentage increase to its quarterly cash dividend.
The strong upward movement reflects a decisive reassessment by institutional market participants as project overhangs diminished and fundamental strength took center stage. Supported by durable secular tailwinds across public infrastructure modernization and energy transition projects, the combination of record margins, healthy backlog expansion, and enhanced shareholder distributions catalyzed widespread buying pressure throughout the trading session.
Technical Analysis of AECOM (ACM)
Technically, AECOM (ACM) shows a MACD (12,26,9) value of 2.359, indicating a buy signal. The RSI at 86.159 suggests overbought condition and the Williams %R at 14.343 suggests overbought condition. Please monitor closely.
Fundamental Analysis of AECOM (ACM)
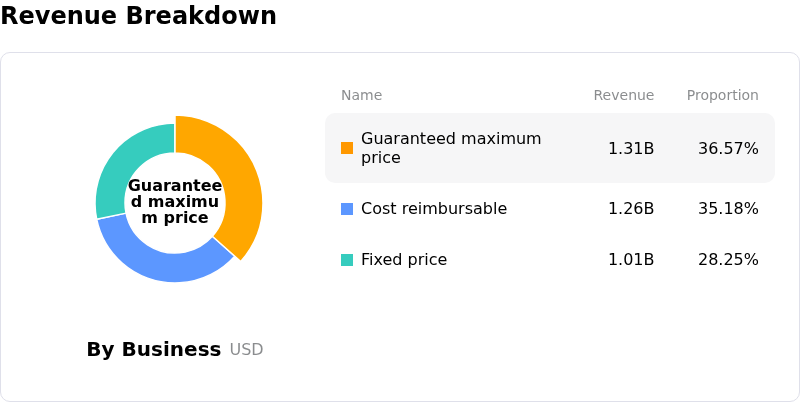
AECOM (ACM) is in the Industrial & Commercial Services industry. Its latest annual revenue is $15.10B, ranking 4 in the industry. The net profit is $293.93M, ranking 11 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $83.01, a high of $106.08, and a low of $65.00.
More details about AECOM (ACM)
Company Specific Risks:
- Top-Line Contraction and Consensus Revenue Miss: In its fiscal fourth-quarter 2026 financial report, AECOM recorded GAAP revenue of $3.88 billion, missing analyst consensus expectations by $222 million and declining 7% year-over-year, driving a 6.5% contraction in full-year revenue to $15.10 billion.
- Persistent Execution Headwinds in Legacy Construction Management: Disclosures in AECOM's latest Form 8-K confirm that lingering execution issues on two legacy at-risk Construction Management projects—which generated substantial project losses earlier in the fiscal year—will continue to burden operating performance and inhibit targeted free cash flow conversion through at least the first half of fiscal 2027.
- Sharp GAAP Earnings and Cash Flow Deterioration: Full-year fiscal 2026 results showed severe GAAP earnings erosion, with net income attributable to AECOM falling 47.7% year-over-year to $293.9 million, diluted EPS dropping 41% to $2.84, and annual free cash flow contracting nearly 50% to $344 million compared to $685.2 million in fiscal 2025.
- Pronounced Operating Weakness in the Americas Segment: Performance within the company's core Americas operational division suffered significant compression, posting a 37% year-over-year decline in full-year adjusted operating income down to $566 million, highlighting underlying margin vulnerability and project-level cost pressures in its largest geography.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.