


Accenture PLC Stock (ACN) Closed Down by 3.40% on Nov 17: A Full Analysis


Accenture PLC (ACN) closed down by 3.40%. The Software & IT Services sector is down by 2.05%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 2.27%; Alphabet Inc Class A (GOOGL) down 1.24%; Meta Platforms Inc (META) down 1.20%.
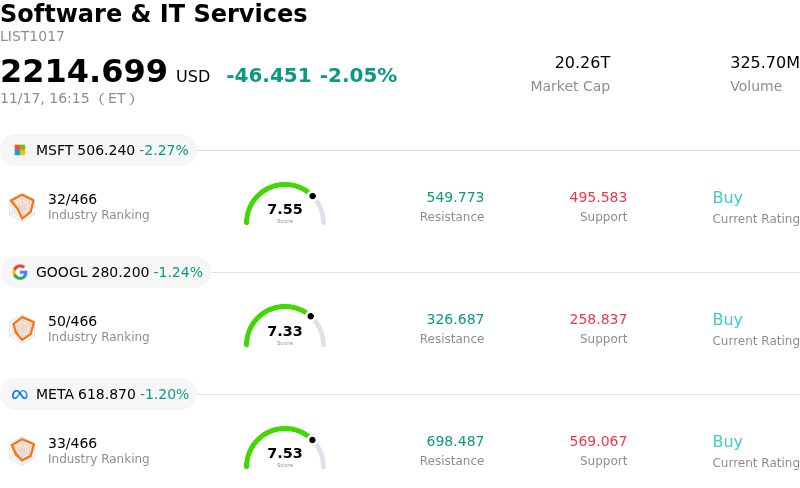
What is driving Accenture PLC (ACN)’s stock price down today?
Accenture experienced notable downward pressure during the trading session, primarily driven by heightened institutional concern regarding enterprise spending appetite and protracted procurement cycles across global consulting engagements. While corporate demand for long-term digital transformation remains structurally intact, near-term capital allocation for discretionary IT projects continues to face intense internal scrutiny. Clients across key verticals, particularly financial services, communications, and media, are prioritizing cost reduction and operational rationalization over large-scale, advisory-heavy transformation programs. This cautious tone has triggered renewed skepticism among market participants regarding the pace at which contracted bookings will convert into recognized top-line revenue over coming quarters.
Compounding these top-line anxieties are structural cross-currents within the enterprise technology services ecosystem. Although the firm has aggressively captured bookings tied to advanced artificial intelligence and cloud modernization, the transition phase poses operational friction. The monetization of generative AI workloads is currently in an advisory and experimentation phase, generating smaller deal sizes relative to traditional ERP rollouts. Concurrently, increasing productivity efficiencies derived from automated code generation and workflow tools are exerting deflationary pressure on conventional billing hours and time-and-materials contracts. Investors are increasingly attentive to whether margin expansion can outpace this legacy pricing compression, especially as wage costs and investments in internal talent reskilling remain elevated.
A broader macro factor influencing the sell-off stems from ongoing monetary policy uncertainty and currency volatility. Prolonged interest rate tightness has elevated borrowing costs for multinational corporations, further incentivizing CFOs to defer non-essential consulting expenditure and demand shorter payback horizons on tech investments. Meanwhile, a resilient U.S. dollar continues to present translation headwinds for the company given its vast international revenue footprint. These macroeconomic constraints, paired with recent cautious commentary across peer IT services providers, have prompted Wall Street analysts to trim short-term organic growth projections and adjust multiple expectations.
From a portfolio positioning standpoint, institutional asset managers appear to be de-risking high-valuation IT services names in favor of either hyper-growth infrastructure plays or more defensive, cash-generative software franchises. In the absence of an immediate catalyst signaling an inflection in discretionary corporate budgets, Accenture remains vulnerable to sentiment-driven multiple compression. Near-term price discovery will largely hinge on management’s ability to defend operating margins through disciplined cost controls and demonstrate accelerated revenue conversion from its strategic technology partnerships.
Technical Analysis of Accenture PLC (ACN)
Technically, Accenture PLC (ACN) shows a MACD (12,26,9) value of -7.768, indicating a neutral signal. The RSI at 48.768 suggests neutral condition and the Williams %R at 96.480 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Accenture PLC (ACN)
Accenture PLC (ACN) is in the Software & IT Services industry. Its latest annual revenue is $74.18B, ranking 6 in the industry. The net profit is $8.37B, ranking 13 in the industry. Company Profile
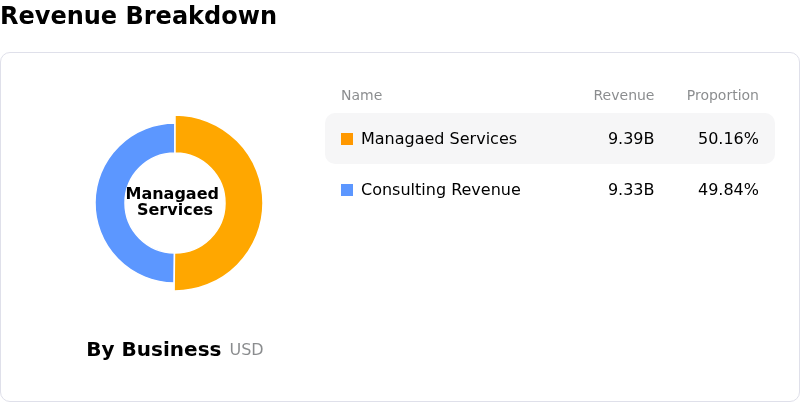
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $237.59, a high of $329.00, and a low of $185.71.
More details about Accenture PLC (ACN)
Company Specific Risks:
- AI-Induced Pricing Deflation and Margin Compression: Enterprise clients are demanding that productivity gains from artificial intelligence be passed through as contractual discounts, resulting in lower realized pricing across several consulting segments and threatening operating margin expansion as billable hours face disintermediation.
- Contract Backlog Erosion and Discretionary Deferrals: Analyst scrutiny has intensified over an observed contraction in remaining performance obligations (RPO), which dipped from $38 billion to $37 billion, signaling that clients are deferring large-scale managed service agreements and delaying discretionary corporate IT spend.
- Subdued Organic Growth Masked by Acquisition Dependence: Projections for fiscal constant-currency growth of 3% to 6% rely heavily on inorganic revenue additions funded by a multi-billion-dollar acquisition budget, leaving core organic expansion at a sluggish ~3% run-rate that trails historical performance.
- Valuation Friction and Executive Insider Divestments: Institutional downgrades to Neutral from firms such as Baird reflect concerns that post-rally multiples fully discount near-term recovery, while recent regulatory filings detailing heavy insider share liquidations—including substantial ownership reductions by senior regional leadership—have triggered profit-taking.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.