


Cloudflare Inc Stock (NET) Moved Down by 3.24% on Nov 17: A Full Analysis


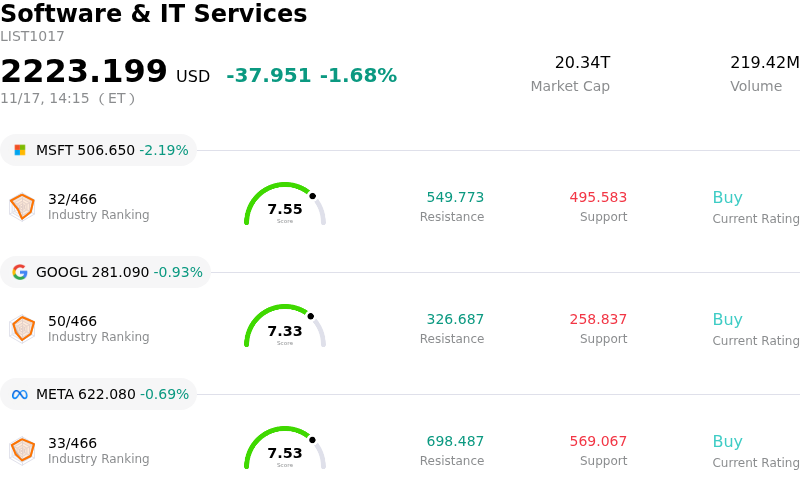
Cloudflare Inc (NET) moved down by 3.24%. The Software & IT Services sector is down by 1.68%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 2.14%; Alphabet Inc Class A (GOOGL) down 0.90%; Meta Platforms Inc (META) down 0.69%.
What is driving Cloudflare Inc (NET)’s stock price down today?
Cloudflare experienced notable downward pressure during the trading session, primarily driven by a broader rotation out of high-valuation software equities alongside macroeconomic headwinds. As a leading player in edge computing, content delivery, and cybersecurity infrastructure, the company trades at a premium multiple relative to the broader software-as-a-service sector. Consequently, intraday upticks in benchmark sovereign yields and shifting expectations around central bank monetary easing have catalyzed valuation compression across high-beta technology names, prompting institutional desks to trim exposure in favor of more defensive asset classes.
From an industry perspective, institutional investors remain cautious regarding enterprise IT budget discipline and longer sales cycles. While demand for Zero Trust architecture, network security, and secure access service edge solutions remains structurally sound, corporate procurement teams continue to scrutinize large contract commitments. Increased competition from both entrenched hyperscalers and specialized cybersecurity vendors has also raised questions about near-term pricing power and net retention expansion, leading some portfolio managers to de-risk holdings ahead of broader market developments.
Furthermore, capital allocation priorities and the monetization trajectory of artificial intelligence workloads continue to be heavily evaluated by the market. Cloudflare has invested aggressively in expanding its global distributed network to support edge inference and developer-focused serverless environments. While this positions the firm favorably for long-term distributed computing demand, the market in the near term is intensely focused on capital expenditure efficiency and the precise timeline for meaningful revenue contributions from these new product suites.
Market sentiment and positioning dynamics also contributed to the intraday retreat. Heightened volatility across growth equities triggered programmatic selling and quantitative risk-off signals, exacerbating the downside momentum. In the absence of an immediate fundamental catalyst, the pullback reflects tactical rebalancing and profit-taking rather than a structural deterioration in the company’s competitive moat. Looking forward, institutional sentiment will hinge on the company’s ability to sustain top-line growth, accelerate enterprise contract closures, and demonstrate margin leverage amidst ongoing macroeconomic uncertainty.
Technical Analysis of Cloudflare Inc (NET)
Technically, Cloudflare Inc (NET) shows a MACD (12,26,9) value of 3.986, indicating a neutral signal. The RSI at 44.141 suggests neutral condition and the Williams %R at 44.868 suggests buy condition. Please monitor closely.
Fundamental Analysis of Cloudflare Inc (NET)
Cloudflare Inc (NET) is in the Software & IT Services industry. Its latest annual revenue is $2.17B, ranking 122 in the industry. The net profit is $-102.27M, ranking 536 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $346.54, a high of $430.00, and a low of $160.00.
More details about Cloudflare Inc (NET)
Company Specific Risks:
- Gross Margin Erosion from AI Infrastructure Scaling: Gross margin contracted sequentially by 70 basis points and 290 basis points year-over-year to 72.4%, as elevated network capital expenditures (reaching 14% to 15% of revenue) and mounting server infrastructure costs needed to support agentic AI workloads and the Workers platform compress unit profitability.
- Persistent GAAP Losses and Stock-Based Compensation Dilution: Despite headline non-GAAP profitability, the company recorded a widening GAAP operating loss of $67.9 million and a GAAP net loss of $34.1 million, weighed down by $174.1 million in quarterly stock-based compensation expenses, an $11 million restructuring charge, and a $10.7 million legal settlement reserve.
- Revenue Durability Risk Tied to Variable Consumption Contracts: Top-line outperformance has increasingly depended on customer burn rates from variable "pool-of-funds" commitments rather than predictable recurring subscription schedules, which analysts warn creates quarterly revenue unpredictability and customer budget exhaustion risks into fiscal year-end.
- Extreme Valuation Disconnect and Sell-Side Downgrade Exposure: Trading at an elevated revenue multiple and negative GAAP price-to-earnings ratio, the stock faces persistent institutional derisking pressure, highlighted by sell-side firms reiterating Sell ratings with price targets as low as $190—representing steep downside from prevailing market prices.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.