


Palo Alto Networks Inc Stock (PANW) Moved Down by 3.37% on Nov 17: Facts Behind the Movement


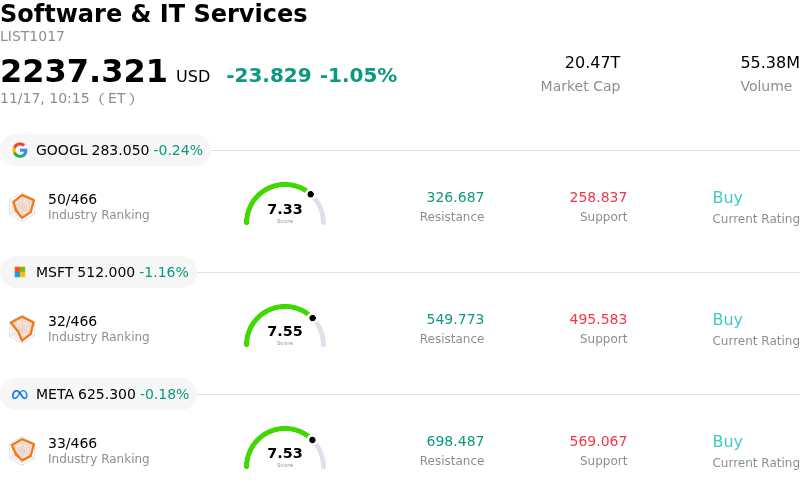
Palo Alto Networks Inc (PANW) moved down by 3.37%. The Software & IT Services sector is down by 1.05%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) down 0.25%; Microsoft Corp (MSFT) down 1.28%; Meta Platforms Inc (META) down 0.29%.
What is driving Palo Alto Networks Inc (PANW)’s stock price down today?
Palo Alto Networks faced notable selling pressure during the session as institutional market participants engaged in tactical de-risking ahead of the company's fiscal first-quarter financial results. Heading into the earnings release, options markets have priced in significant post-earnings volatility, encouraging growth-oriented funds and hedge funds to trim exposure and lock in gains following an extended advance. Historical precedent has also heightened institutional caution, as the stock has frequently experienced sharp pullbacks following past quarterly reports when results or near-term outlooks failed to meet elevated buy-side expectations.
Valuation sensitivity serves as a primary catalyst compounding the downward momentum. Palo Alto Networks continues to trade at a substantial premium relative to both legacy enterprise software and cybersecurity peers. This high multiple leaves virtually no margin for execution errors, rendering the share price exceptionally vulnerable to valuation compression. In an environment where enterprise budgets face ongoing scrutiny and capital allocation remains selective, any perceived deceleration in top-line growth or conservative forward guidance poses asymmetric downside risk.
At the operational and industry level, investors are closely examining the near-term economics of the company's strategic push toward platformization. While consolidating disparate point security products into an integrated ecosystem strengthens long-term customer retention and expands wallet share, the transition frequently entails short-term trade-offs. These dynamics, including multi-year contract restructuring, promotional incentives, and deferred billing terms, create interim ambiguity regarding organic revenue visibility, next-generation annual recurring revenue expansion, and free cash flow conversion. Concurrently, investors are monitoring integration costs and dilution risks tied to large-scale identity security and cloud-focused acquisitions.
Broader technology market sentiment also exerted downward pressure on high-multiple cybersecurity equities. Extended procurement cycles among corporate chief information security officers, coupled with macro concerns over the pace of enterprise software budget expansion, have generated cross-currents throughout the security sector. As institutional managers reposition portfolios toward defensive assets, Palo Alto Networks absorbed heightened liquidity outflows, reflecting pre-earnings caution rather than an immediate deterioration in the structural cybersecurity demand landscape.
Technical Analysis of Palo Alto Networks Inc (PANW)
Technically, Palo Alto Networks Inc (PANW) shows a MACD (12,26,9) value of -7.320, indicating a sell signal. The RSI at 33.858 suggests neutral condition and the Williams %R at 99.883 suggests oversold condition. Please monitor closely.
Media Coverage of Palo Alto Networks Inc (PANW)
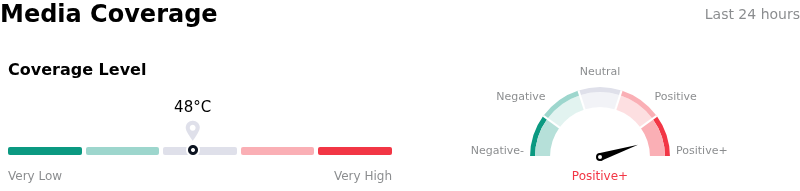
In terms of media coverage, Palo Alto Networks Inc (PANW) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Palo Alto Networks Inc (PANW)
Palo Alto Networks Inc (PANW) is in the Software & IT Services industry. Its latest annual revenue is $11.48B, ranking 34 in the industry. The net profit is $307.00M, ranking 90 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $401.69, a high of $525.00, and a low of $190.00.
More details about Palo Alto Networks Inc (PANW)
Company Specific Risks:
- Pre-Earnings De-Risking and Post-Print Drawdown History: Institutional positioning has turned defensive ahead of the November 18 fiscal Q1 financial release, exacerbated by market scrutiny highlighting that the stock has dropped after six of its last eight quarterly reports, triggering intraday liquidation and technical deterioration below key moving averages.
- Stretched Valuation Multiple Vulnerability: Trading at an elevated valuation exceeding 75x forward earnings, the stock exhibits heightened asymmetric downside volatility into earnings, amplified by recent sell-side price target reductions (such as Jefferies lowering its target to $400) warning of zero tolerance for top-line or billings deceleration.
- Platformization Transition and Billing Friction: Ongoing corporate push toward customer "platformization" introduces operational headwinds, as aggressive vendor consolidation incentives, contract restructuring, and deferred billing terms place temporary pressure on revenue timing and free cash flow conversion.
- Aggressive M&A Integration and Capital Depletion: Rapid deal-making activity—including active talks to acquire AI-agent security startup Clutch Security for roughly $500 million in cash following multiple prior transactions—stokes investor apprehension regarding integration friction, operating margin dilution, and heightened execution risks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.