


Salesforce Inc Stock (CRM) Opened Down by 5.00% on Nov 17: What Investors Need To Know


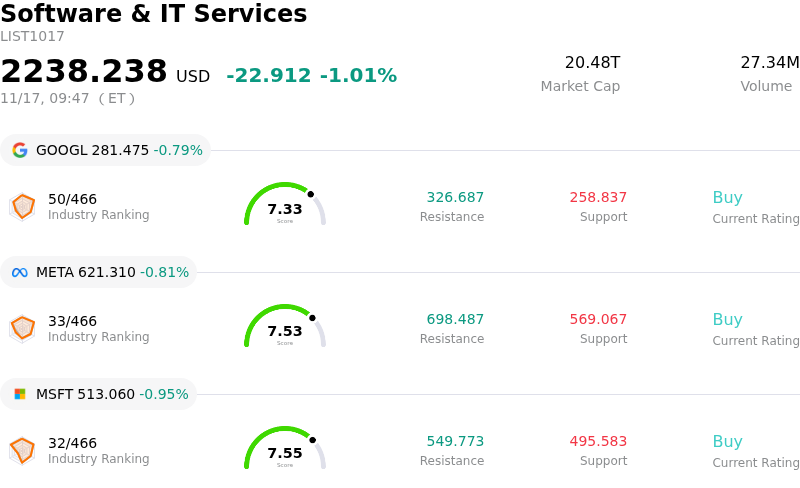
Salesforce Inc (CRM) opened down by 5.00%. The Software & IT Services sector is down by 1.01%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) down 0.86%; Meta Platforms Inc (META) down 0.89%; Microsoft Corp (MSFT) down 0.95%.
What is driving Salesforce Inc (CRM)’s stock price down today?
Salesforce is facing pronounced downward pressure today, driven by renewed investor skepticism regarding the pace of enterprise software monetization and broader valuation compression across large-cap cloud platforms. Channel checks and industry commentary indicate that corporate information technology budgets remain tightly scrutinized, with procurement officers continuing to extend deployment timelines and rationalize software spending. This ongoing friction in enterprise deal closures has reignited concerns over near-term subscription revenue acceleration, prompting institutional market participants to trim exposure.
A central overhang weighing on the stock centers on the commercialization timeline of the company’s autonomous artificial intelligence platforms. While enterprise interest in digital agent frameworks and automated customer management workflows has been robust, institutional investors are demonstrating diminished patience for pilot programs that have yet to translate into meaningful expansion in net new annual recurring revenue. Lingering uncertainty persists regarding whether consumption-based AI agent monetization can swiftly counterbalance the structural growth deceleration observed across mature seat-based licensing models, particularly as specialized workflow competitors and cloud hyperscalers intensify pricing competition.
The decline is further magnified by portfolio rebalancing and broader factor rotation within the technology sector. Asset allocators have selectively rotated liquidity out of high-multiple enterprise software providers and into infrastructure and semiconductor beneficiaries that offer more immediate capital expenditure visibility. Furthermore, persistent macroeconomic crosscurrents and sensitivity to interest rate expectations continue to depress terminal value assumptions for software-as-a-service equities. Until management demonstrates tangible acceleration in top-line bookings and clear margin expansion stemming from its next-generation platform offerings, the shares are likely to contend with heightened volatility and cautious institutional sentiment.
Technical Analysis of Salesforce Inc (CRM)
Technically, Salesforce Inc (CRM) shows a MACD (12,26,9) value of -3.964, indicating a sell signal. The RSI at 29.733 suggests sell condition and the Williams %R at 99.808 suggests oversold condition. Please monitor closely.
Media Coverage of Salesforce Inc (CRM)
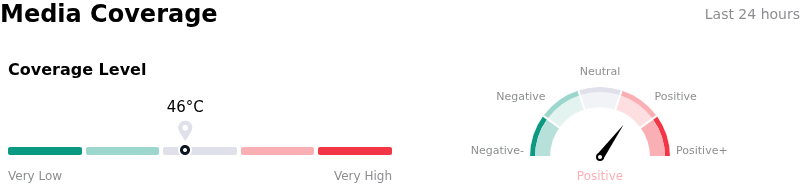
In terms of media coverage, Salesforce Inc (CRM) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Salesforce Inc (CRM)
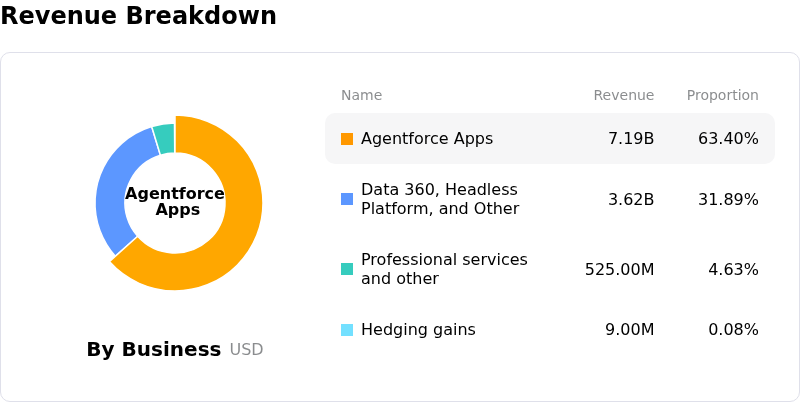
Salesforce Inc (CRM) is in the Software & IT Services industry. Its latest annual revenue is $41.52B, ranking 14 in the industry. The net profit is $7.46B, ranking 15 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $290.06, a high of $475.00, and a low of $195.00.
More details about Salesforce Inc (CRM)
Company Specific Risks:
- Balance Sheet Leverage and Credit Rating Downgrades: S&P Global Ratings downgraded Salesforce's issuer credit rating from "A+" to "A" due to elevated net leverage and debt expansion driven by an aggressive M&A roll-up—including acquisitions of Informatica ($9.5 billion), Braze ($5.7 billion), and Cresta (~$2.7 billion)—alongside a massive $25 billion debt-funded share repurchase program.
- Deceleration in Core Organic Subscription Growth: Institutional analysts are increasingly concerned that top-line performance remains masked by acquired revenues rather than true organic expansion, with persistent secular softness across core enterprise offerings like Tableau and Commerce Cloud dragging down underlying subscription billings.
- Lagging Agentforce Monetization and Revenue Conversion: Despite aggressive promotional redirection toward agentic AI, Wall Street commentary continues to cite a disconnect between platform adoption and actual revenue inflection, as Agentforce contributions remain too small to deliver the sustained organic acceleration demanded by the market.
- Competitive Disruption to Seat-Based Pricing Models: The emergence of AI-native CRM competitors and aggressive expansions by enterprise incumbents like ServiceNow and Oracle are exerting pricing pressure on traditional seat-based SaaS subscriptions, creating execution and margin risks as Salesforce is forced to re-engineer its monetization strategy.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.