


Alibaba Group Holding Ltd Stock (BABA) Moved Down by 3.25% on Nov 16: What Signal Does It Send?


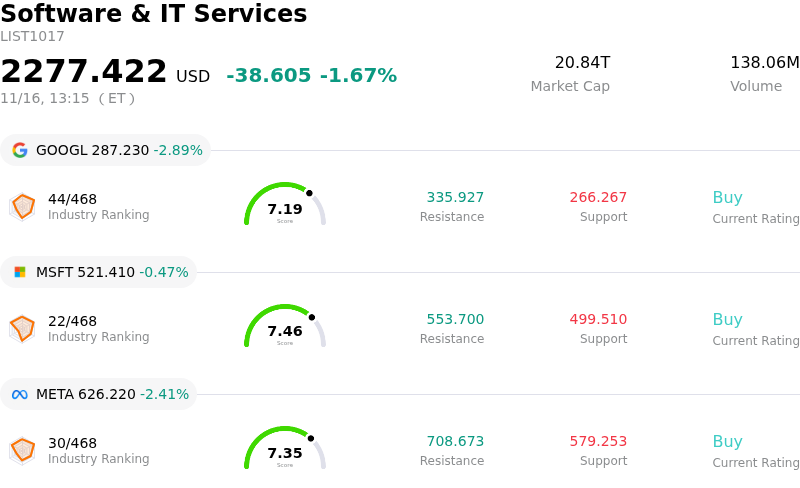
Alibaba Group Holding Ltd (BABA) moved down by 3.25%. The Software & IT Services sector is down by 1.67%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) down 2.89%; Microsoft Corp (MSFT) down 0.47%; Meta Platforms Inc (META) down 2.41%.
What is driving Alibaba Group Holding Ltd (BABA)’s stock price down today?
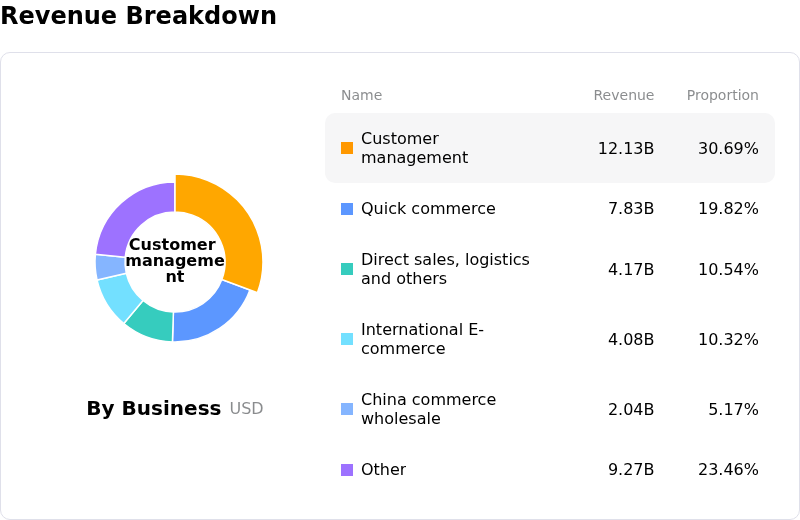
Alibaba Group has faced pronounced intraday selling pressure as market participants digest post-Singles' Day shopping metrics and recalibrate expectations for domestic retail recovery. Early industry readouts indicate that while consumer engagement remained steady, intense platform competition necessitated deep discounting and expanded merchant subsidies across Taobao and Tmall. This heavy promotional environment has heightened investor concern that gross merchandise volume growth is failing to translate into higher customer management revenues, ultimately threatening to dilute core e-commerce operating margins in the near term.
Compounding concerns around core retail profitability is the company's sustained capital expenditure trajectory. Alibaba continues to commit substantial resources toward expanding its Cloud Intelligence infrastructure, developing proprietary artificial intelligence capabilities, and scaling its international digital commerce footprint. While these strategic pivots are essential for building a multi-engine growth framework over the long run, institutional investors are increasingly demanding tangible returns on invested capital. The absence of immediate top-line acceleration from these high-investment segments has spurred momentum-driven profit-taking and defensive portfolio rebalancing among institutional holders.
Broader macroeconomic and currency dynamics are also magnifying the retreat across Chinese technology American Depositary Receipts. Persistent strength in the U.S. dollar has weighed on the offshore yuan, mechanically reducing the translated dollar value of Alibaba's predominantly mainland-generated cash flows. Simultaneously, lingering ambiguity regarding the timing and efficacy of broader consumer stimulus measures, paired with ongoing geopolitical friction around advanced semiconductor access, has elevated the overall equity risk premium. Facing these cross-currents, market sentiment has shifted defensively, driving sharp intraday volatility as funds reduce exposure pending clearer catalysts for margin stabilization and consumer demand revival.
Technical Analysis of Alibaba Group Holding Ltd (BABA)
Technically, Alibaba Group Holding Ltd (BABA) shows a MACD (12,26,9) value of -1.817, indicating a sell signal. The RSI at 30.444 suggests neutral condition and the Williams %R at 99.498 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Alibaba Group Holding Ltd (BABA)
Alibaba Group Holding Ltd (BABA) is in the Software & IT Services industry. Its latest annual revenue is $144.14B, ranking 5 in the industry. The net profit is $14.91B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $184.14, a high of $220.10, and a low of $95.00.
More details about Alibaba Group Holding Ltd (BABA)
Company Specific Risks:
- U.S. AI Chip Export Curbs: Emerging regulatory reports indicate the U.S. Commerce Department is finalizing expanded restrictions to block Chinese technology firms from accessing advanced AI processors via third-party offshore data centers, directly threatening Alibaba's cloud computing capacity and hardware rental arrangements through overseas partners.
- Capital Expenditure Burden and Cash Flow Drain: Massive capital deployment toward AI data center buildouts alongside ongoing loss-making subsidies for quick-commerce delivery services continue to depress operating margins and generate substantial free cash flow outflows, escalating analyst concern ahead of the upcoming earnings print.
- Core Retail Monetization Headwinds: Taobao and Tmall Group face persistent pricing pressure and market share attrition from aggressive discounting by low-cost rivals such as PDD Holdings and ByteDance, stalling Customer Management Revenue (CMR) growth and requiring elevated defensive merchant subsidies.
- Cross-Border Regulatory and Compliance Liability: Tighter scrutiny from global enforcement bodies—including U.S. Department of Justice policing of merchant transactions on overseas platforms and Chinese regulatory crackdowns on e-commerce product standards—imposes recurring legal risks, mandatory compliance costs, and friction on international digital commerce operations.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.