


HSBC Holdings PLC Stock (HSBC) Moved Up by 3.27% on Nov 9: What Signal Does It Send?


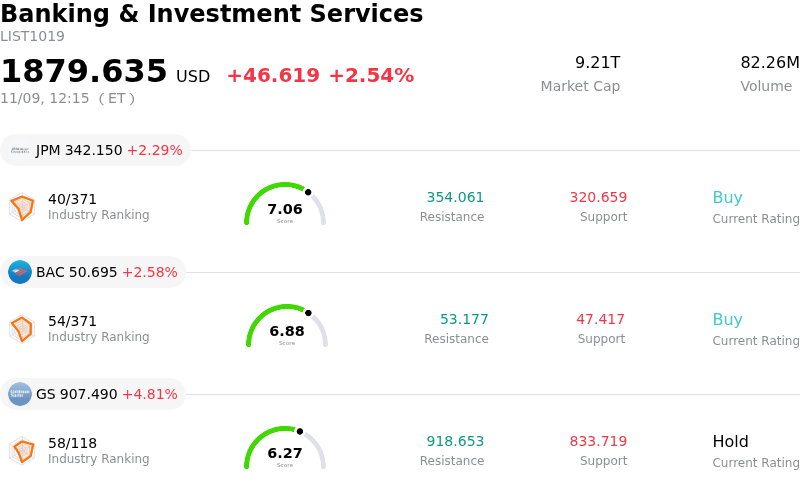
HSBC Holdings PLC (HSBC) moved up by 3.27%. The Banking & Investment Services sector is up by 2.54%. The company outperformed the industry. Top 3 stocks by turnover in the sector: JPMorgan Chase & Co (JPM) up 2.29%; Bank of America Corp (BAC) up 2.58%; Goldman Sachs Group Inc (GS) up 4.81%.
What is driving HSBC Holdings PLC (HSBC)’s stock price up today?
HSBC experienced notable upward momentum during today’s session, driven by a combination of strengthening operational fundamentals, supportive capital return dynamics, and improving sentiment across global financial institutions. Institutional investors responded favorably to signs of enduring profitability in the bank’s core commercial and wealth management franchises, alongside constructive broader market conditions.
A primary catalyst supporting the stock is the continued durability of HSBC’s net interest income, reinforced by sticky deposit margins in key Asian hubs and the United Kingdom. Although major central banks have entered gradual easing cycles, yield curve behavior and disciplined liability pricing have allowed the bank to preserve net interest margins better than previously anticipated. Concurrently, momentum in the wealth and personal banking division has provided high-quality, fee-based revenue diversification, offsetting lower asset yields and driving optimism around return on tangible equity targets.
Shareholder return frameworks remain a critical pillar underpinning current equity demand. Ongoing execution of substantial share repurchase programs, coupled with dependable dividend payouts, continues to provide consistent technical support and enhance earnings per share accretion. Investors have increasingly viewed HSBC as a disciplined capital allocator, particularly as management continues to streamline operations, divest lower-return Western assets, and redeploy capital toward higher-yielding cross-border trade and Asian wealth corridors.
Macroeconomic conditions and risk reassessments have also played an important role in today’s gains. Market concerns regarding exposure to regional commercial real estate and mainland China credit risks have continued to moderate, supported by targeted policy interventions and proactive balance sheet provisioning over prior quarters. With credit loss provisions stabilizing within manageable institutional tolerances, asset quality anxiety has subsided, clearing the path for valuation multiple expansion.
Overall, the day’s advance reflects an alignment of robust non-interest income growth, shareholder-friendly capital deployment, and diminishing asset quality headwinds. As global institutional flows rotate toward resilient, cash-generative banking franchises with strong international trade connectivity, HSBC remains well-positioned to sustain market interest, provided macroeconomic stability across its primary operating corridors holds firm.
Technical Analysis of HSBC Holdings PLC (HSBC)
Technically, HSBC Holdings PLC (HSBC) shows a MACD (12,26,9) value of 0.834, indicating a neutral signal. The RSI at 47.574 suggests neutral condition and the Williams %R at 40.317 suggests buy condition. Please monitor closely.
Fundamental Analysis of HSBC Holdings PLC (HSBC)
HSBC Holdings PLC (HSBC) is in the Banking & Investment Services industry. Its latest annual revenue is $69.62B, ranking 4 in the industry. The net profit is $21.10B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $101.03, a high of $112.05, and a low of $90.00.
More details about HSBC Holdings PLC (HSBC)
Company Specific Risks:
- Net Interest Margin and Funding Cost Compression: Analyst commentary highlights sustained downside pressure on banking Net Interest Income (NII) as upcoming central bank rate cut cycles and aggressive commercial deposit competition increase funding costs, threatening to compress net interest margins.
- Capital Ratio Slippage Below Target Band: HSBC's Common Equity Tier 1 (CET1) ratio fell to 13.9%, slipping below management's guided target corridor of 14.0% to 14.5%, raising institutional concern regarding capital adequacy headroom and future share buyback capacity.
- Persistent Credit Quality Stress in Commercial Real Estate: The bank faces ongoing credit impairment risks from defaults in mainland China and Hong Kong commercial real estate lending, alongside recent one-off credit loss provisions that continue to weigh on profitability.
- Stagnant Wealth Revenue and Top-Line Softness: Market sentiment has deteriorated following flat growth in wealth fees and other non-interest income, creating a top-line revenue miss that undermines management's strategy to offset declining interest rate margins through fee-based Asian wealth expansion.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.