


Eli Lilly and Co Stock (LLY) Moved Up by 3.09% on Nov 9: Facts Behind the Movement


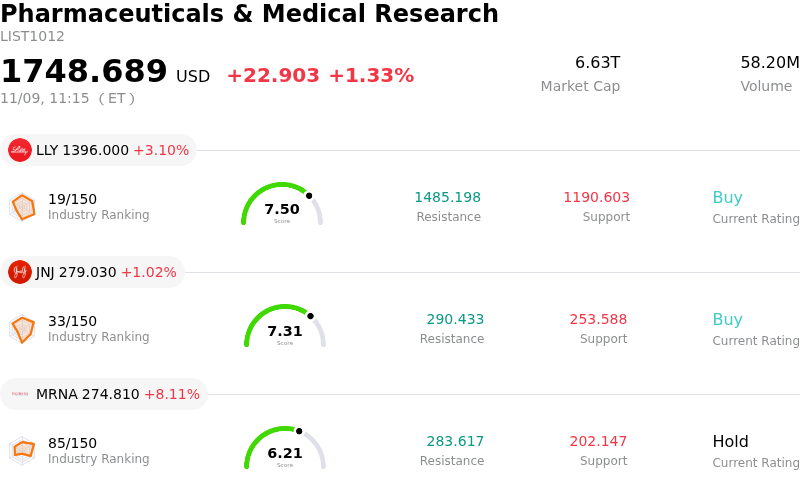
Eli Lilly and Co (LLY) moved up by 3.09%. The Pharmaceuticals & Medical Research sector is up by 1.33%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) up 3.10%; Johnson & Johnson (JNJ) up 1.02%; Moderna Inc (MRNA) up 7.66%.
What is driving Eli Lilly and Co (LLY)’s stock price up today?
Eli Lilly and Company demonstrated robust upward momentum today as institutional investors responded favorably to sustained commercial tailwinds across its core metabolic portfolio and positive sentiment surrounding its next-generation pipeline. Market participants continue to reward the company for its dominant position in the rapidly expanding obesity and type 2 diabetes markets, where demand for tirzepatide-based therapies remains resilient against broader macroeconomic uncertainties.
A primary catalyst supporting the stock is the ongoing expansion of the commercial runway for tirzepatide, marketed as Mounjaro and Zepbound. Broadening insurance coverage and progress in label expansions—particularly in related comorbidities such as obstructive sleep apnea, cardiovascular risk mitigation, and metabolic dysfunction-associated steatohepatitis—have reinforced long-term revenue visibility. Simultaneously, encouraging pipeline updates across oral GLP-1 receptor agonists and multi-incretin candidates have strengthened investor confidence that the company can sustain its therapeutic leadership well into the next decade.
Operational execution has further bolstered the bullish thesis. Lilly has continued to aggressively deploy capital into manufacturing and filling capacity, easing prior supply bottlenecks and improving product availability across global distribution networks. This manufacturing scale not only protects existing market share against competing GLP-1 alternatives but also erects high barriers to entry for biosimilars and late-stage market entrants. Consequently, sell-side analysts have maintained an optimistic posture, pointing to sustained operating leverage and superior margin expansion relative to the broader large-cap biopharmaceutical peer group.
From a portfolio strategy standpoint, the advance reflects broader institutional appetite for mega-cap growth assets with non-cyclical cash flows. In an environment characterized by selective risk-taking, Lilly represents a premier high-visibility earnings compounder, blending defensive healthcare characteristics with secular biotechnology growth. While premium valuation multiples require continued flawless clinical and commercial execution, current price action underscores strong institutional sponsorship driven by an exceptional growth profile and durable competitive advantages.
Technical Analysis of Eli Lilly and Co (LLY)
Technically, Eli Lilly and Co (LLY) shows a MACD (12,26,9) value of 7.994, indicating a buy signal. The RSI at 66.251 suggests neutral condition and the Williams %R at 29.174 suggests buy condition. Please monitor closely.
Media Coverage of Eli Lilly and Co (LLY)
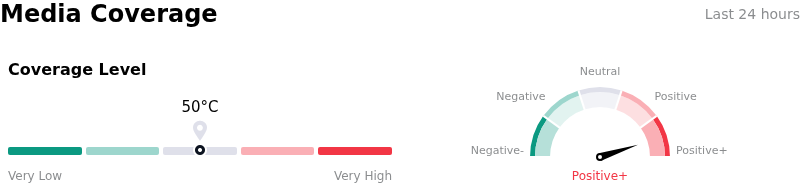
In terms of media coverage, Eli Lilly and Co (LLY) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Eli Lilly and Co (LLY)
Eli Lilly and Co (LLY) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $65.18B, ranking 4 in the industry. The net profit is $20.64B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $1438.09, a high of $1690.00, and a low of $891.22.
More details about Eli Lilly and Co (LLY)
Company Specific Risks:
- Net Price Realization Erosion: Recent financial disclosures and analyst assessments highlight that worldwide realized prices dropped 15%—with international realized prices falling 29%—driven by expanding patient enrollment in discounted channels such as Medicare's GLP-1 Bridge program, posing severe margin-compression headwinds despite aggregate volume expansion.
- New Therapy Commercial Underperformance: Eli Lilly's newly launched oral weight-loss therapy, Foundayo, missed consensus expectations by delivering $184 million against the $217 million forecast, indicating early commercial adoption friction and prescription growth softness against competing metabolic treatments.
- Elevated Valuation Multiple Vulnerability: Trading at a premium multiple of roughly 40x to 44x forward earnings, institutional analysts warn that approximately $2 billion of non-recurring revenue recognized in 2026 creates an unfavorable comparable hurdle for 2027, leaving shares highly susceptible to multiple contraction if organic volume growth decelerates.
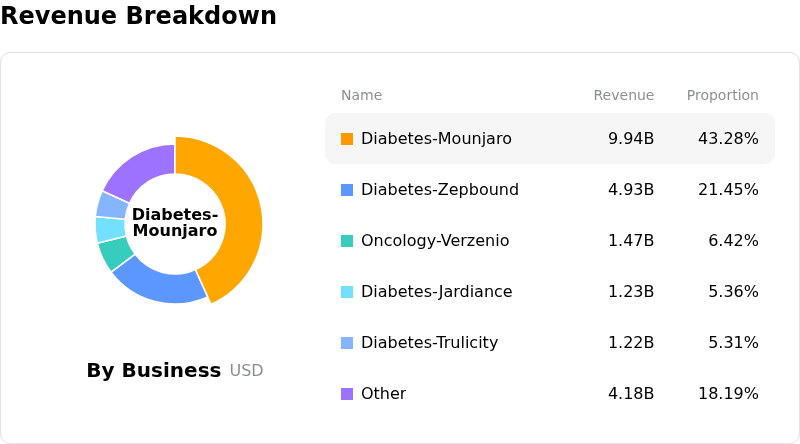
- Severe GLP-1 Franchise Concentration: With roughly two-thirds of total company revenues dependent on its core incretin portfolio (Mounjaro and Zepbound), escalating pricing concessions in its duopoly against Novo Nordisk and rising reimbursement pushback from commercial payers and employers threaten long-term revenue durability.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.