


Alphabet Inc Class A Stock (GOOGL) Opened Up by 3.44% on Nov 9: Facts Behind the Movement


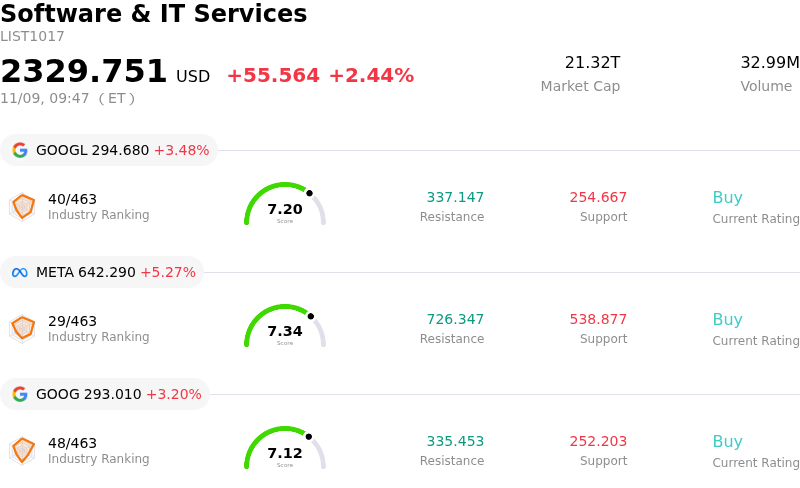
Alphabet Inc Class A (GOOGL) opened up by 3.44%. The Software & IT Services sector is up by 2.44%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class A (GOOGL) up 3.44%; Meta Platforms Inc (META) up 5.45%; Alphabet Inc Class C (GOOG) up 3.19%.
What is driving Alphabet Inc Class A (GOOGL)’s stock price up today?
Alphabet shares demonstrated notable upward momentum during the session, driven by strengthening institutional confidence in the company's enterprise artificial intelligence roadmap and the ongoing operational leverage within its core digital ad and cloud segments. Investors responded favorably to mounting evidence that enterprise integration of generative AI tools is directly bolstering Google Cloud Platform's market position, helping Alphabet maintain sustained top-line acceleration while reinforcing its competitive moat against key hyperscaler peers.
A primary catalyst supporting sentiment is the market's evolving perception of search monetization in the generative AI era. Concerns regarding search margin cannibalization and alternative query engines have meaningfully receded as Alphabet's integrated search overviews and native AI commercial formats demonstrate resilient click-through engagement and steady pricing power. Concurrently, YouTube's multi-format monetization, particularly across short-form video and connected television inventory, continues to capture shifted linear broadcast budgets, providing solid cash-flow visibility that underpins current valuation multiples.
From an industry and macro perspective, sustained appetite for large-cap tech infrastructure plays has directed institutional inflows toward balance sheets capable of supporting high capital expenditure cycles without sacrificing capital returns. Alphabet's robust free cash flow generation, combined with steady share repurchase activity, provides defensive stability while simultaneously funding proprietary silicon deployment and data center expansion. These infrastructure investments are increasingly viewed by portfolio managers as durable cost-efficiency levers that will expand operating margins over the medium term.
While antitrust scrutiny and regulatory developments surrounding ad-tech and distribution agreements remain persistent background risks, market participants are currently discounting immediate operational disruption, choosing instead to prioritize solid fundamentals and disciplined operational expenditure. With positive revisions in institutional forward earnings estimates and stable broader macroeconomic indicators, Alphabet continues to attract strategic long-term accumulation across institutional portfolios.
Technical Analysis of Alphabet Inc Class A (GOOGL)
Technically, Alphabet Inc Class A (GOOGL) shows a MACD (12,26,9) value of -4.530, indicating a sell signal. The RSI at 38.040 suggests neutral condition and the Williams %R at 70.389 suggests sell condition. Please monitor closely.
Media Coverage of Alphabet Inc Class A (GOOGL)
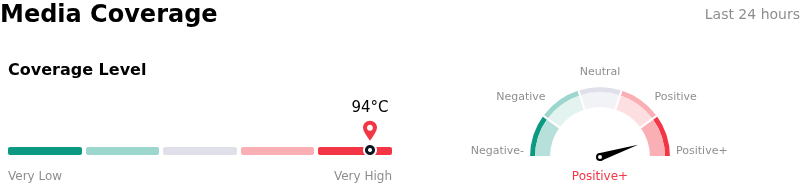
In terms of media coverage, Alphabet Inc Class A (GOOGL) shows a coverage score of 94, indicating a very high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Alphabet Inc Class A (GOOGL)
Alphabet Inc Class A (GOOGL) is in the Software & IT Services industry. Its latest annual revenue is $402.84B, ranking 2 in the industry. The net profit is $132.17B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $402.31, a high of $500.00, and a low of $300.00.
More details about Alphabet Inc Class A (GOOGL)
Company Specific Risks:
- Search Ad Monetization Compression: Core Search advertising revenue growth has decelerated as search traffic shifts toward AI Overviews and conversational AI Mode, where monetization rates and paid-click conversion lag significantly behind traditional search result links.
- CapEx Surge and Free Cash Flow Deficit: Sustained full-year capital expenditure guidance of $195 billion to $205 billion for AI data centers has driven quarterly free cash flow to negative $9.07 billion, accelerating depreciation expenses and compressing consolidated operating profit margins.
- Escalating Long-Term Purchase Obligations and Compute Rationing: Regulatory disclosures highlighted over $1 trillion in long-term purchase obligations alongside tens of billions in incremental commitments, while internal infrastructure constraints are forcing capacity rationing between external Google Cloud enterprise clients and internal DeepMind training workloads.
- Antitrust Distribution Headwinds and Valuation Multiple Overhang: Institutional downgrades and target cuts reflect persistent regulatory risks following federal antitrust rulings, specifically the legal and financial vulnerability of multi-billion-dollar default search distribution agreements with Apple and mobile device manufacturers.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.