


Intel Corp Stock (INTC) Moved Down by 3.68% on Nov 4: Drivers Behind the Movement


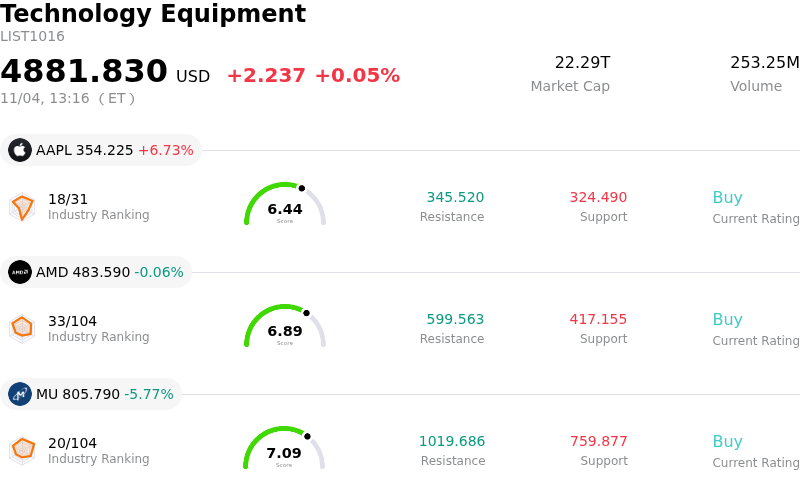
Intel Corp (INTC) moved down by 3.68%. The Technology Equipment sector is up by 0.05%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 6.76%; Advanced Micro Devices Inc (AMD) down 0.06%; Micron Technology Inc (MU) down 5.61%.
What is driving Intel Corp (INTC)’s stock price down today?
Intel Corporation experienced downward pressure as extended post-earnings selling sentiment, cautious forward guidance, and structural headwinds in the personal computer market continued to weigh on investor confidence. Although the company delivered top-line growth and beat quarterly earnings expectations driven by robust demand in its data center and artificial intelligence division, market participants focused heavily on the disappointing forward-looking outlook. Management projected a sequential drop in quarterly revenue and a sharp contraction in gross margins, falling significantly short of consensus expectations on Wall Street. The broader Client Computing Group faces ongoing cyclical pressure, with elevated component costs and sluggish consumer upgrade cycles curbing PC unit demand.
Compounding top-line concerns are operational constraints and manufacturing challenges. Recent operational disruptions at key production facilities have exacerbated near-term supply tightness for server processors while imposing direct margin headwinds. At the same time, the Intel Foundry segment continues to operate at a substantial financial loss while working to scale next-generation process technology and secure major external fab clients. This creates execution risk as capital expenditures remain elevated while external revenue contributions from non-captive customers develop gradually.
The cautious corporate outlook triggered a wave of price target reductions and rating adjustments from major Wall Street investment banks, accelerating institutional portfolio rebalancing. Analysts expressed concern over the persistent weakness in the client PC ecosystem and the timeline required for the foundry turnaround to generate meaningful free cash flow. While long-term opportunities in enterprise server hardware and domestic semiconductor manufacturing remain intact, near-term risk sentiment remains dominated by margin pressure, supply chain bottlenecks, and persistent PC market cyclicality.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of -7.483, indicating a sell signal. The RSI at 22.809 suggests sell condition and the Williams %R at 97.543 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
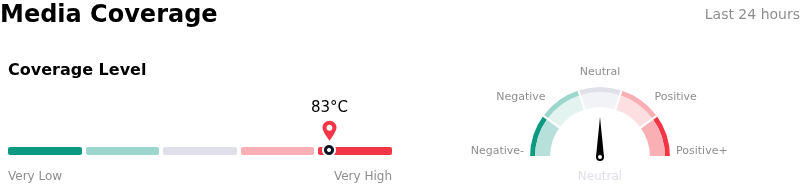
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 83, indicating a very high level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $95.16, a high of $160.00, and a low of $70.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Severe Fourth-Quarter Guidance Miss and Margin Compression: Intel projected Q4 revenue of $15.0 billion to $16.0 billion and non-GAAP EPS of $0.25, sharply underperforming Wall Street consensus estimates of $17.1 billion and $0.43 respectively, while forecasting gross margins to shrink from 44.1% to 38.0%.
- Persistent PC Market Slump and Memory Cost Inflation: Management warned that Client Computing Group revenue is expected to drop over 20% sequentially with market weakness lingering into mid-2027, amplified by surging DRAM memory prices that are dampening PC upgrade demand.
- Operational Bottlenecks and Fab Disruption: Supply chain shortfalls in raw materials alongside an operational disruption at Intel's Fab 28 facility in Kiryat Gat, Israel, are capping data center chip supply and impacting an estimated $600 million in revenue across two quarters.
- Elevated Capex and Negative Free Cash Flow Outlook: Management confirmed plans for sharply increased capital expenditures and warned that the company will not generate positive free cash flow in 2027, triggering widespread institutional downgrades and target price reductions.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.