


ASML Holding NV Stock (ASML) Moved Down by 3.09% on Nov 4: What Signal Does It Send?


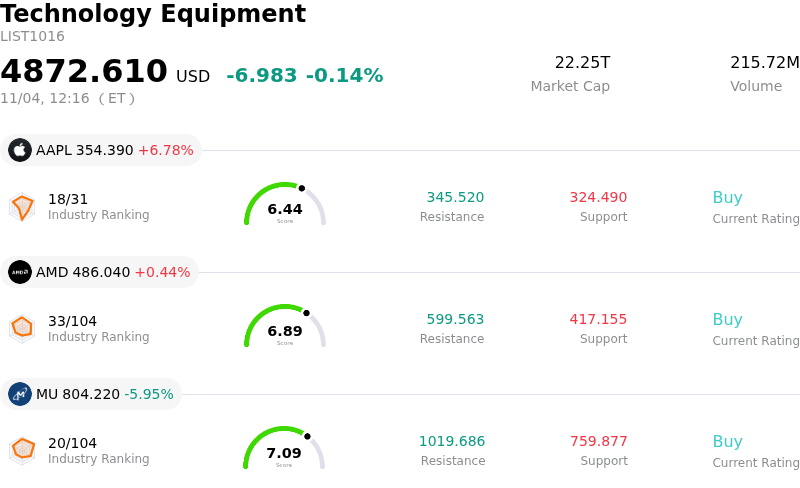
ASML Holding NV (ASML) moved down by 3.09%. The Technology Equipment sector is down by 0.14%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 6.68%; Advanced Micro Devices Inc (AMD) up 0.44%; Micron Technology Inc (MU) down 5.81%.
What is driving ASML Holding NV (ASML)’s stock price down today?
ASML Holding N.V. experienced notable downward pressure and heightened intraday volatility, primarily driven by persistent investor cautiousness surrounding international trade policy friction and tighter export controls on advanced semiconductor manufacturing technology. As regulatory scrutiny regarding the sales and servicing of deep ultraviolet lithography systems in key overseas markets remains high, market participants continue to price in potential headwinds to equipment delivery schedules and revenue normalization in target regions. Although secular demand for extreme ultraviolet tools remains anchored by global artificial intelligence infrastructure investments, broader macro risk-off sentiment across the technology landscape has weighed on high-valuation semiconductor equipment leaders.
From a fundamental and operational perspective, the market is evaluating a bifurcated demand environment across the semiconductor supply chain. Leading foundries and memory chipmakers are concentrating capital expenditures heavily on cutting-edge AI applications, while demand recovery across mature nodes, automotive electronics, and personal computing markets progresses more gradually. Furthermore, execution dynamics surrounding the rollout of next-generation High-NA EUV equipment platforms and supply chain capacity constraints have prompted institutional investors to take a disciplined view on near-term order timing. Recent corporate developments, such as dividend adjustments and ongoing share buyback activity, also contributed to near-term trading volume as funds rebalance portfolios.
Looking ahead, institutional sentiment toward ASML reflects a balance between short-term policy headwinds and its structural technological moat. The company retains a near-monopolistic leadership position in advanced lithography, which remains an essential enabler for next-generation chip architecture. While headline risk and macroeconomic uncertainty may trigger temporary price pullbacks, market focus will center on upcoming quarterly order bookings, key customer fab expansion progress in major geographic hubs, and regulatory updates to determine whether current price weakness offers a favorable position for long-term equity allocation.
Technical Analysis of ASML Holding NV (ASML)
Technically, ASML Holding NV (ASML) shows a MACD (12,26,9) value of -24.032, indicating a sell signal. The RSI at 35.418 suggests neutral condition and the Williams %R at 91.093 suggests oversold condition. Please monitor closely.
Fundamental Analysis of ASML Holding NV (ASML)
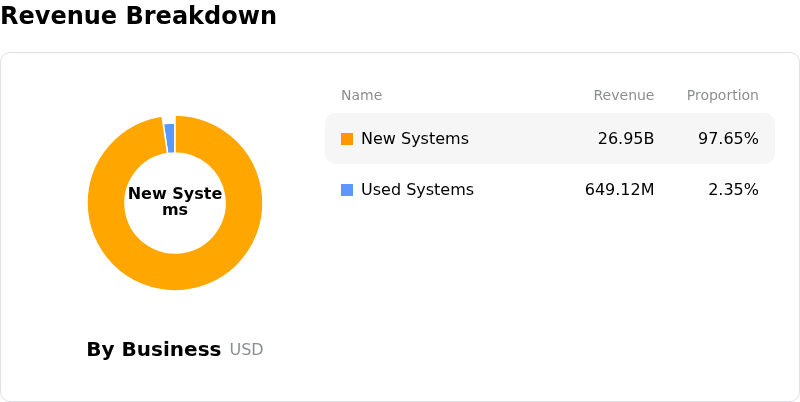
ASML Holding NV (ASML) is in the Technology Equipment industry. Its latest annual revenue is $36.83B, ranking 8 in the industry. The net profit is $10.83B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2210.62, a high of $2858.00, and a low of $1450.00.
More details about ASML Holding NV (ASML)
Company Specific Risks:
- Geopolitical Export Controls on DUV Machinery: U.S. legislative efforts, including the proposed MATCH Act, alongside tightening Dutch trade controls, threaten to expand export bans to cover deep ultraviolet (DUV) immersion tools and servicing to Chinese clients, endangering a segment that previously accounted for 20% to 33% of ASML's annual revenue.
- Severe Production Capacity Bottlenecks: Management's acknowledgment that planned tool manufacturing capacity through 2027 and 2028 will fail to meet customer demand positions ASML as an operational bottleneck, exposing the company to execution risks, heavy capital expenditure burdens, and potential market share erosion.
- Customer CapEx Shocks and Order Deferrals: Severe financial shocks and lowered guidance from key chipmaking clients, such as Intel, paired with mounting market skepticism over the ROI of massive AI capital expenditure, heighten the risk of delayed or canceled orders for high-margin Extreme Ultraviolet (EUV) lithography systems.
- Multiple Contraction and Dividend Headwinds: Trading at an elevated price-to-earnings multiple relative to discounted cash flow models and semiconductor sector peers leaves the stock uniquely vulnerable to steep institutional profit-taking, a risk compounded by recent sequential dividend reductions.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.