


HSBC Holdings PLC Stock (HSBC) Moved Up by 4.54% on Nov 4: Key Drivers Unveiled


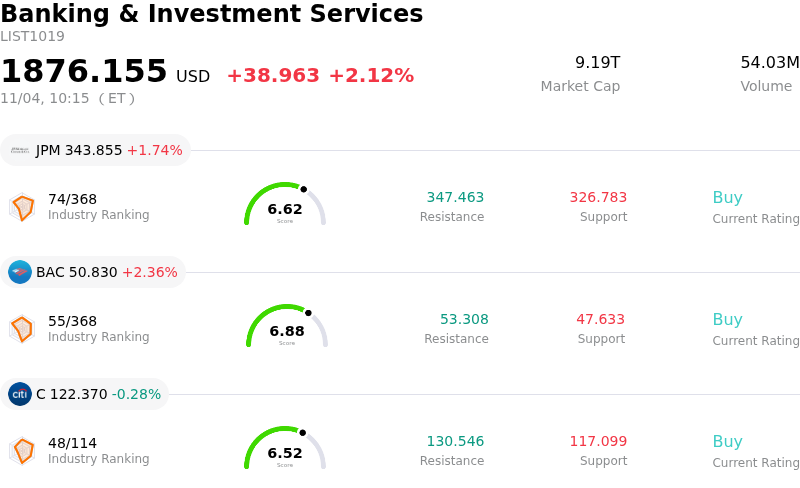
HSBC Holdings PLC (HSBC) moved up by 4.54%. The Banking & Investment Services sector is up by 2.12%. The company outperformed the industry. Top 3 stocks by turnover in the sector: JPMorgan Chase & Co (JPM) up 1.77%; Bank of America Corp (BAC) up 2.37%; Citigroup Inc (C) down 0.19%.
What is driving HSBC Holdings PLC (HSBC)’s stock price up today?
The upward momentum in HSBC shares reflects a strong technical rebound following recent selling pressure, combined with accelerating institutional interest around the bank's active capital return program. After experiencing downside pressure following its third-quarter financial release—where short-term revenue and earnings metrics missed street consensus—the stock entered oversold technical territory. This technical discount created an attractive entry window for value-oriented global financial sector investors. Momentum was further amplified as market participants responded to the bank's ongoing share repurchase program, which commenced in late October, alongside the approaching ex-dividend date for its quarterly distribution. The systematic buyback execution across major global exchanges has effectively absorbed selling pressure and bolstered market liquidity.
Fundamentally, investor sentiment is being anchored by solid momentum within HSBC’s core strategic pillars, particularly its Asian wealth management franchise. Despite broader macroeconomic uncertainties and shifting interest rate dynamics, the firm reported substantial net new money inflows of thirty-eight billion dollars in its Asian wealth division during the third quarter, driving cumulative year-to-date inflows past ninety-five billion dollars. Fee income expansion across cross-border wealth services in key regional hubs has provided a crucial buffer against fluctuating interest rates. Coupled with strict internal expense discipline and organizational simplification initiatives that keep annual cost growth near target levels, the underlying operational efficiency reinforces confidence in the bank's target return on tangible equity of at least seventeen percent through 2028.
Looking ahead, regulatory capital trajectory and balance sheet management remain central to the institutional bull thesis. Management's updated guidance regarding impending Basel 3.1 capital framework standards indicates potential risk-weighted asset relief of forty to fifty basis points starting in 2027. This anticipated capital flexibility reduces balance sheet constraints and provides structural firepower to sustain multi-year share repurchases while maintaining a fifty percent dividend payout target. While macroeconomic headwinds in key operating regions and deposit repricing risks require continued monitoring, the convergence of aggressive capital return actions, structural wealth management inflows, and technical oversold support has driven a sharp positive repricing in the equity.
Technical Analysis of HSBC Holdings PLC (HSBC)
Technically, HSBC Holdings PLC (HSBC) shows a MACD (12,26,9) value of -0.415, indicating a sell signal. The RSI at 39.798 suggests neutral condition and the Williams %R at 66.951 suggests sell condition. Please monitor closely.
Fundamental Analysis of HSBC Holdings PLC (HSBC)
HSBC Holdings PLC (HSBC) is in the Banking & Investment Services industry. Its latest annual revenue is $69.62B, ranking 4 in the industry. The net profit is $21.10B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $101.03, a high of $112.05, and a low of $90.00.
More details about HSBC Holdings PLC (HSBC)
Company Specific Risks:
- Q3 Earnings and Revenue Shortfall: HSBC missed consensus estimates in its recent Q3 2026 earnings release, posting EPS of $2.10 versus the $2.20 expected and revenue of $18.68 billion against the $18.98 billion estimate, driving multi-session selling pressure across its ADR shares.
- Wealth Unit Earnings Reversal: Revenue within HSBC's strategic Wealth division contracted 3% quarter-over-quarter, triggering a 14% drop in segment pre-tax profit to $1.1 billion and alarming institutional analysts who view Asian wealth management as the bank's primary growth engine.
- Capital Cushion Deterioration Below Target Range: The group's Common Equity Tier 1 (CET1) capital ratio slipped from 14.1% to 13.9%, falling below management's official target corridor of 14.0%–14.5% due to elevated risk-weighted assets and debt security valuation adjustments, creating capital allocation and dividend sustainability concerns.
- Deposit Pricing Pressure and Margin Risk: Rising competitive pressure on customer deposit rates is driving funding costs higher, creating a downside risk to net interest margin (NIM) trajectories and threatening net interest income targets if cheap deposit migration accelerates.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.