


Alphabet Inc Class C Stock (GOOG) Opened Up by 3.43% on Nov 4: What Signal Does It Send?


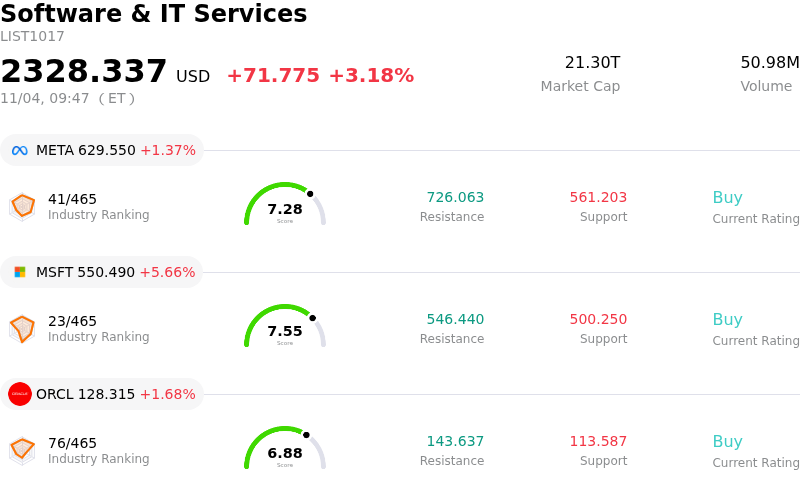
Alphabet Inc Class C (GOOG) opened up by 3.43%. The Software & IT Services sector is up by 3.18%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 1.56%; Microsoft Corp (MSFT) up 5.61%; Oracle Corp (ORCL) up 1.90%.
What is driving Alphabet Inc Class C (GOOG)’s stock price up today?
After experiencing heavy sell-off pressure following its third-quarter earnings announcement, Alphabet Inc. recorded a strong positive rebound driven by opportunistic dip-buying and institutional repositioning. Market sentiment pivoted as investors re-evaluated the company's compressed valuation metrics, which had fallen to deeply discounted levels relative to historical averages and broader mega-cap technology peers. The initial negative market reaction was heavily focused on near-term headwinds, including elevated capital expenditures and a squeeze on free cash flow resulting from massive AI infrastructure buildouts. However, value-oriented institutional investors recognized that the post-earnings sell-off was overdone, sparking a technical bounce and short-covering across major exchanges.
A major catalyst supporting the upward price action is the growing investor appreciation for Alphabet's robust cloud and artificial intelligence growth trajectory. Reassuring fundamentals from Google Cloud, which saw revenue double year-over-year supported by a massive multi-hundred-billion-dollar backlog, provided clear evidence that aggressive capital commitments are beginning to translate into enterprise demand. Furthermore, expanding partnerships across enterprise and government sectors, including prospective involvement in large-scale defense data initiatives and deepened commitments from major AI developers, have reinforced confidence in the long-term return profile of Alphabet's technical infrastructure.
Broad-based strength across the broader technology sector further amplified positive risk sentiment, providing macro tailwinds for mega-cap software and digital advertising leaders. While concerns regarding short-term capital intensity and search revenue growth remain key monitoring points, the combination of attractive fundamental valuations, persistent cloud momentum, and long-term artificial intelligence monetization has temporarily outweighed defensive positioning. Institutional market participants appear to be refocusing on Alphabet's structural competitive advantages and dominant user ecosystem as the initial volatility surrounding quarterly earnings clears.
Technical Analysis of Alphabet Inc Class C (GOOG)
Technically, Alphabet Inc Class C (GOOG) shows a MACD (12,26,9) value of -10.244, indicating a sell signal. The RSI at 30.148 suggests neutral condition and the Williams %R at 79.209 suggests sell condition. Please monitor closely.
Media Coverage of Alphabet Inc Class C (GOOG)
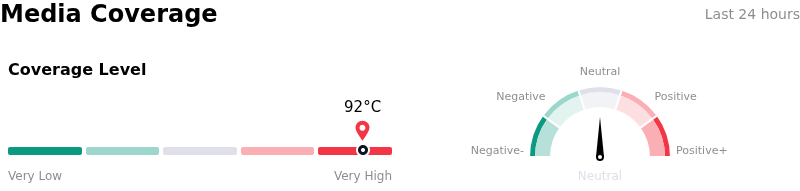
In terms of media coverage, Alphabet Inc Class C (GOOG) shows a coverage score of 92, indicating a very high level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Alphabet Inc Class C (GOOG)
Alphabet Inc Class C (GOOG) is in the Software & IT Services industry. Its latest annual revenue is $402.84B, ranking 1 in the industry. The net profit is $132.17B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $400.21, a high of $475.00, and a low of $332.00.
More details about Alphabet Inc Class C (GOOG)
Company Specific Risks:
- Search Revenue Monetization Dilution: Google Search advertising revenue growth decelerated to 12% in the third quarter, underperforming consensus estimates ($63.4 billion vs. $64.5 billion expected) as the shift toward AI Mode queries generates lower advertising yields than traditional search formats.
- Negative Free Cash Flow and Capital Expenditure Inflation: Aggressive investments in artificial intelligence hardware pushed free cash flow negative to -$9.1 billion, while management raised projected capital expenditures toward $200 billion for 2026 and up to $300 billion for 2027, severely restricting share repurchases and prompting new debt offerings.
- Compute Capacity Constraints and Forgone Cloud Revenue: Google Cloud is deliberately sacrificing near-term enterprise revenue to prioritize scarce compute resources for internal DeepMind development, with executive commentary signaling severe capacity shortages for onboarding new enterprise cloud clients through 2027.
- Substantial Purchase Obligations and Regulatory Outflows: Recent SEC disclosures highlighted $98.5 billion in additional off-balance-sheet purchase commitments alongside a $5.2 billion cash outlay to settle regulatory penalties, compounding liquidity concerns during a period of record capital outlays.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.